Crime Trends Businesses Should Monitor
Crime remains a significant concern for businesses of all sizes.
From small retailers and growing startups to large corporations, criminal activities can affect revenue, disrupt operations, damage reputations and weaken customer confidence.
As businesses adopt digital payments, online sales platforms and more complex supply chains, the risks they face continue to evolve. Criminals can target physical premises, exploit weaknesses in digital systems, impersonate trusted business partners or manipulate employees into revealing confidential information.
Deloitte’s Nigeria Cybersecurity Outlook 2026 identifies AI-assisted scams, ransomware, identity fraud and attacks targeting digital access as important cybersecurity concerns for Nigerian organisations. These developments highlight the need for businesses to monitor emerging threats rather than rely entirely on traditional security measures.
Understanding these crime trends can help business owners identify warning signs, protect their assets and prepare effective responses. Here are seven major areas that businesses should monitor.
1. Cybercrime and Ransomware Attacks
Cybercrime is one of the most important security concerns for businesses that rely on computers, mobile devices, online platforms and cloud-based services.
Criminals may attempt to steal customer information, access financial accounts, disrupt company websites or lock employees out of essential files. Ransomware attacks, in particular, can interrupt daily operations when criminals encrypt business data and demand payment for its recovery.
Small businesses face these risks too. A company does not need to operate a large digital platform to become a target. Even a small online retailer may hold customer details, payment records and supplier information that criminals can exploit.
Businesses should monitor unusual login attempts, unexpected changes to account permissions, suspicious emails and unexplained disruptions to their systems.
To reduce exposure, companies should use multifactor authentication, install security updates promptly, restrict access to sensitive information and maintain regular backups. Employees should also know how to report suspicious messages before interacting with them.
2. Phishing, Impersonation and AI-Powered Scams
Criminals increasingly exploit trust to deceive employees, customers and business owners. Instead of breaking directly into a system, they may persuade someone to transfer money, disclose a password or approve a fraudulent transaction.
Phishing emails, fake invoices, fraudulent supplier requests and messages impersonating senior executives are common examples of this approach.
Artificial intelligence can make these scams more convincing. Criminals may use it to create polished emails, imitate familiar writing styles or produce convincing audio and video impersonations.
For example, an employee in a Nigerian company might receive a WhatsApp message that appears to come from the managing director. The message requests an urgent transfer to a new bank account. Without an independent verification process, the employee could approve a fraudulent payment.
Businesses should establish clear procedures for verifying payment instructions and changes to supplier bank details. Employees should confirm unusual requests through a separate, trusted communication channel rather than relying on the message itself.
3. Payment Fraud and Digital Transaction Scams
Digital payments have made it easier for businesses to collect money, pay suppliers and serve customers across different locations. However, these conveniences also create opportunities for fraud.
Businesses should watch for fake payment alerts, forged transfer receipts, unauthorised refunds, stolen payment credentials and disputes involving transactions that customers do not recognise.
For businesses that accept bank transfers, a screenshot or SMS notification should not serve as the sole proof of payment. Staff should confirm that the money has actually entered the appropriate account before releasing goods or completing an order.
E-commerce businesses should also monitor repeated failed transactions, unusual order patterns and refund requests that do not match normal customer behaviour.
Reliable transaction records, appropriate payment-provider safeguards and regular account reconciliation can help businesses detect irregularities early.
4. Employee Theft and Internal Fraud
Not every business loss originates outside the organisation. Employees, contractors or other authorised individuals may misuse their access to money, stock, equipment or confidential information.
Internal fraud can take several forms, including unauthorised discounts, manipulated invoices, false expense claims, inventory diversion and the theft of cash or merchandise.
For example, a warehouse employee might record fewer items than the company actually receives, allowing some stock to disappear without immediately triggering an investigation. Similarly, an employee responsible for refunds could approve transactions that do not meet company policy.
Businesses should monitor unexplained inventory shortages, repeated accounting adjustments, unusual refund activity and discrepancies between sales records and cash received.
However, an irregularity does not automatically prove wrongdoing. Errors, weak processes and poor record-keeping can produce similar warning signs.
Companies should separate financial responsibilities, conduct routine stock checks, maintain clear approval procedures and investigate concerns fairly. Strong internal controls protect honest employees as well as business assets.
5. Robbery, Shoplifting and Physical Security Threats
Physical crime continues to affect retailers, warehouses, offices, restaurants and other commercial establishments.
Shoplifting can create repeated losses for businesses selling groceries, electronics, clothing, cosmetics and other easily resold products. Robbery presents an additional risk because it may involve threats or physical violence against employees and customers.
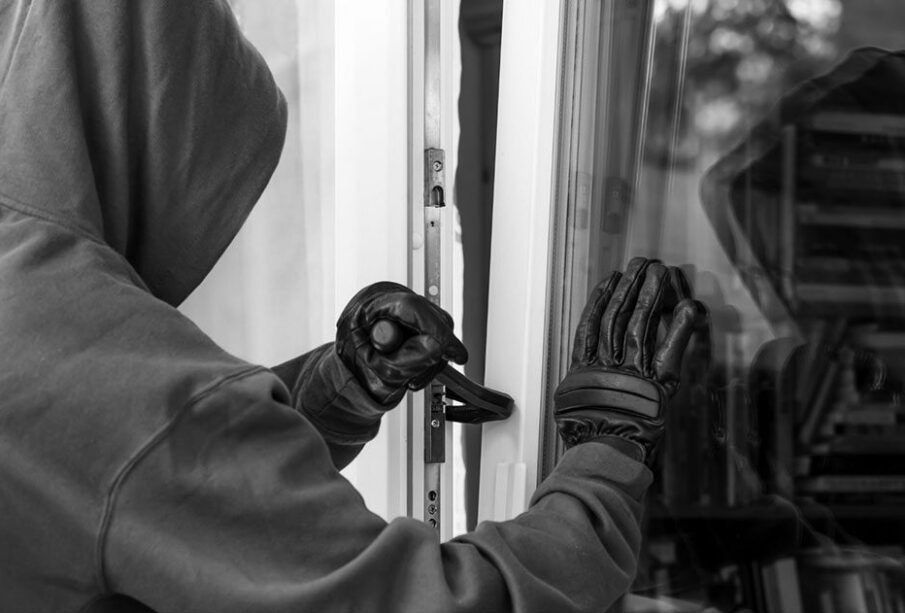
Businesses should pay attention to recurring stock shortages, suspicious activity around entrances and exits, attempted break-ins and security weaknesses around cash-handling areas.
For Nigerian businesses, location-specific risks also matter. A shop operating late at night may require different security arrangements from an office that closes before evening. A warehouse in an isolated industrial area may need stronger access controls and perimeter monitoring.
Practical safeguards include adequate lighting, secure storage, properly maintained locks, appropriate CCTV coverage and clear procedures for opening and closing premises.
Most importantly, employee safety should take priority over merchandise or cash. Staff should not be encouraged to physically confront suspected offenders.
6. Cargo Theft and Supply Chain Crime
Businesses that transport, store or distribute goods face risks beyond their own premises. Criminals may target delivery vehicles, warehouses, distribution centres and goods moving between suppliers and customers.
Cargo theft can affect manufacturers, wholesalers, retailers, logistics companies and small businesses that depend on regular deliveries.
In African markets, where businesses often rely on long-distance road transport and multiple distribution partners, a missing shipment can cause more than a direct financial loss. It may also delay customer orders, interrupt production and damage relationships with retailers.
Companies should monitor unexplained delivery delays, missing inventory, inconsistent tracking records and unexpected changes to delivery instructions.
To strengthen supply chain security, businesses can verify delivery partners, document the movement of goods, restrict access to shipment information and maintain clear handover records. GPS tracking and electronic proof of delivery may also improve visibility where appropriate.
Businesses should review their procedures whenever shipments repeatedly go missing or delivery records fail to match physical stock.
7. Social Media Fraud and Brand Impersonation
Social media has become an important sales and customer-service channel for many African businesses. Companies use platforms such as Instagram, Facebook, TikTok and WhatsApp to advertise products, answer enquiries and receive orders.
Unfortunately, criminals can exploit this visibility by creating fake accounts, copying product images, impersonating customer-service representatives or advertising products they do not intend to deliver.
A fraudulent account might use a business’s logo and contact details to convince customers to transfer money to an unauthorised account. Customers who lose money may then blame the genuine company, even when it had no involvement in the transaction.
Businesses should regularly check for suspicious accounts using their names, logos and product photographs. They should also monitor customer complaints about unusual payment requests and misleading advertisements.
Companies can reduce confusion by publishing their official contact details, explaining their payment procedures and providing a clear way for customers to report suspected impersonation.
When a fraudulent account appears, businesses should preserve relevant evidence, report it through the platform’s official channels and warn customers through verified accounts where necessary.
How Businesses Can Build a Stronger Crime Prevention Strategy
Monitoring crime trends is only useful when businesses turn that information into practical action. An effective strategy should combine prevention, early detection and a clear response plan.
Conduct regular risk assessments
Identify the assets that matter most to the business, including cash, inventory, customer records, equipment and supplier relationships. Then examine how each asset could be stolen, misused or compromised.
Train employees to recognise warning signs
Staff should understand how to identify suspicious messages, verify unusual payment requests, protect customer information and report incidents. Training should cover both digital and physical threats.
Maintain accurate financial and inventory records
Reconcile bank transactions, sales records, invoices and stock movements regularly. Reliable records make it easier to distinguish ordinary mistakes from unusual patterns that require investigation.
Establish clear reporting procedures
Employees should know whom to contact when they notice suspicious activity. Businesses should record incidents consistently, protect relevant evidence and investigate concerns without making unsupported accusations.
Review security measures regularly
Criminal tactics and business operations change over time. Review access permissions, payment controls, supplier arrangements, physical security and data backups at regular intervals.
Prepare an incident response plan
Decide in advance what the business will do after a suspected cyberattack, fraudulent transfer, robbery or missing shipment. The plan should identify responsible personnel, reporting channels, recovery procedures and steps for protecting affected customers and employees.
Conclusion
Crime trends continue to evolve alongside changes in technology, commerce and business operations. Cyberattacks, payment fraud, AI-assisted impersonation, internal theft, physical robbery, cargo theft and social media scams can all threaten business stability.
For businesses in Nigeria and across Africa, effective crime prevention requires more than installing security cameras or relying on passwords. Companies need accurate records, trained employees, reliable verification procedures and consistent monitoring of both physical and digital activities.
Business owners should also remember that unusual activity is a reason to investigate, not automatic proof of a crime. Fair investigations and well-designed controls help protect employees, customers and business partners.
By reviewing security practices regularly and responding promptly to warning signs, businesses can reduce avoidable losses, strengthen customer confidence and improve their ability to operate when security incidents occur.

Leave a reply


Africa’s Source for Breaking News | Entertainments | Health | Finance | Sports | Lifestyle and Business News.


