Mobile Money in Egypt
Mobile Money in Egypt: How It Is Changing How Africans Save and Spend
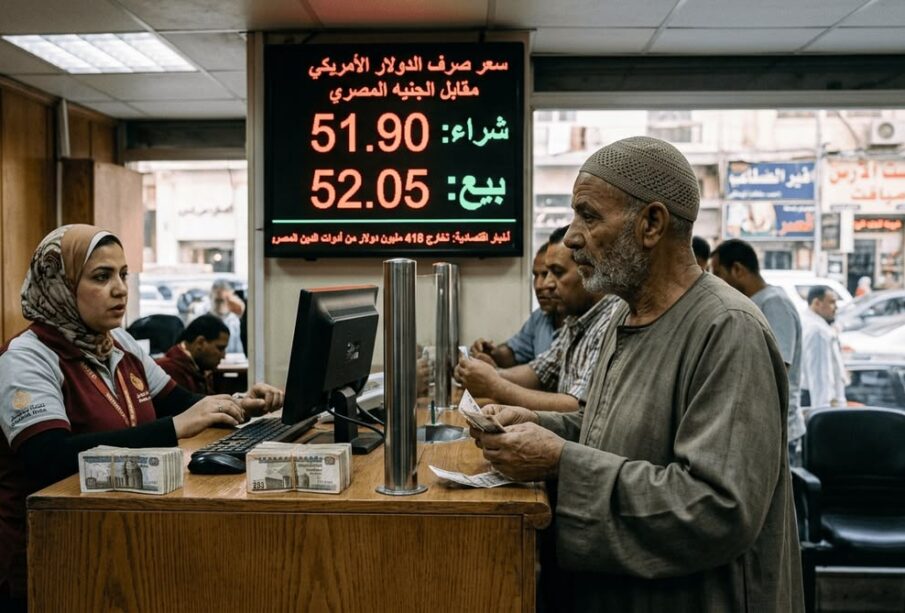
Across Africa, mobile technology is changing how people manage money. From sending funds to family members to paying business expenses, digital financial services are making everyday transactions faster and more convenient. Egypt is an important example of this transformation, with mobile wallets becoming increasingly popular among individuals, traders, and businesses.
The country’s mobile money market has grown significantly as more people embrace digital payments. According to Egypt’s National Telecommunications Regulatory Authority, mobile wallet transactions reached 718 million in the second quarter of 2025, with a total value of approximately EGP 943.4 billion. These figures demonstrate the growing role of digital wallets in everyday financial activities.
Services such as Vodafone Cash, e& Cash, Orange Cash, and WE Pay allow users to transfer money, purchase airtime, and make selected payments using their mobile phones. As adoption increases, mobile money is changing how Egyptians save, spend, and participate in the economy. Its development also offers useful lessons for other African countries seeking to expand financial inclusion.
How Mobile Money Works in Egypt
Mobile money allows people to perform financial transactions through mobile devices without always needing to visit a traditional bank. Depending on the provider and account type, users can send money, receive transfers, pay bills, recharge mobile phones, and withdraw cash through supported channels.
In Egypt, telecommunications companies and financial institutions provide mobile wallet services under the country’s financial regulatory framework. Customers generally need to meet identification and registration requirements before activating an account.
Once registered, users can access supported services through their provider’s application or other available channels. Some transactions require an internet connection, while certain services may work through alternative mobile interfaces.
This accessibility makes mobile wallets useful for people who want convenient financial services without relying entirely on conventional banking procedures.
1. Making Everyday Payments Easier
One of the clearest benefits of mobile money is the convenience it brings to everyday spending. Previously, many cash-based transactions required people to carry physical money, visit payment centres, or arrange transfers in person.
Mobile wallets reduce some of these inconveniences. Users can send money to relatives, pay participating merchants, recharge their phones, and settle eligible bills from their devices.
For example, a worker in Cairo can transfer money to a family member in another Egyptian city without travelling to deliver cash. A small trader can also receive digital payments from customers who prefer not to carry large amounts of money.
These services save time and may reduce the risks associated with transporting cash. However, users should always check transaction fees, transfer limits, and merchant acceptance before relying on a wallet for a particular payment.
2. Helping People Develop Better Saving Habits
Mobile money can make saving more accessible by giving users a convenient place to hold funds digitally. Instead of spending every available banknote, individuals may choose to keep part of their income in a wallet for future expenses.
Consider a market trader who earns different amounts each day. Transferring a portion of those earnings into a separate account or wallet can help the trader organise money for rent, supplies, school fees, and emergencies.
Digital transaction histories can also help users review their spending patterns. By checking incoming and outgoing payments, they can identify unnecessary expenses and plan their budgets more carefully.
However, a mobile wallet is not automatically a savings or investment product. Wallet balances may not earn interest, and the protection offered can differ from that of a regulated savings account. People seeking long-term savings should compare available options and understand the applicable terms.
3. Creating Opportunities for Small Businesses
Small businesses are among the potential beneficiaries of Egypt’s expanding digital payment ecosystem. Many microbusinesses operate with limited administrative resources and depend heavily on daily sales.
Accepting digital payments can help shop owners, independent service providers, and online sellers receive money without handling cash for every transaction. Electronic records can also make it easier to track sales and reconcile payments.
For example, a clothing seller who receives wallet payments can review transaction records when calculating daily revenue. A home-based food business can accept eligible digital transfers from customers ordering meals.
These advantages can support better financial management and improve convenience for customers. Over time, documented transaction activity may also help some businesses demonstrate their financial performance when seeking appropriate financial services.
Nevertheless, business owners should account for transaction charges, maintain accurate records, and protect their accounts against fraud.
4. Expanding Financial Inclusion
Mobile money can connect people with financial services that might otherwise be difficult to access. This matters in communities where bank branches are inconvenient, opening accounts is challenging, or people have limited experience with formal financial institutions.
Egypt’s progress reflects this wider shift. The National Telecommunications Regulatory Authority reported more than 50 million mobile wallets by the end of 2024. Meanwhile, the Central Bank of Egypt reported that financial inclusion reached 77.6% by the end of 2025. The latter measure includes people using bank accounts, Egypt Post accounts, mobile wallets, and prepaid cards, so it should not be interpreted as a mobile-wallet adoption rate alone.
Mobile wallets can be particularly useful for young adults, informal workers, and small entrepreneurs who need practical ways to send and receive money. However, access alone is not enough. Users also need affordable services, reliable networks, suitable identification options, and clear information about their rights.
5. What Other African Countries Can Learn
Egypt’s experience offers several lessons for Africa’s broader digital finance industry.
First, cooperation between regulators, telecommunications companies, banks, and payment providers can help create an environment where digital financial services grow responsibly. Clear rules can encourage innovation while establishing expectations for security and consumer protection.
Second, mobile money becomes more useful when providers offer services that address real needs. Transfers, airtime purchases, bill payments, merchant transactions, and access to formal financial products can encourage people to use digital wallets regularly.
Third, financial education is essential. People need to understand transaction fees, account limits, fraud prevention, and the differences between payment wallets and interest-bearing savings accounts.
Countries such as Nigeria, Ghana, Kenya, and Uganda have their own digital payment systems and regulatory environments. Egypt’s experience does not offer a single model that every country should copy. Instead, it demonstrates the importance of combining accessible technology with consumer trust, effective regulation, and practical services.
6. Challenges That Still Need Attention
Despite its benefits, mobile money faces several challenges. Digital fraud remains a concern, particularly when criminals impersonate service providers or persuade users to reveal personal identification numbers and verification codes.
Network interruptions, forgotten credentials, transaction errors, and service fees can also discourage adoption. Some customers may struggle with digital interfaces or lack confidence in electronic payments.
Providers and regulators must continue strengthening security, improving customer support, and educating users. Individuals can protect themselves by using official applications, keeping verification codes private, checking recipient details before transferring money, and reporting suspicious activity promptly.
Financial inclusion must also extend beyond people who already own smartphones or have reliable internet access. Accessible services and clear support channels are necessary to ensure that digital finance benefits a wider population.
Conclusion
Mobile money is changing how Egyptians send funds, make purchases, manage business income, and approach everyday financial planning. Its growing adoption demonstrates how mobile technology can make financial services more accessible while supporting the development of a digital economy.
For Africa, the opportunity extends beyond replacing cash with electronic payments. Mobile money can encourage better financial organisation, support small businesses, and create pathways into the formal financial system.
However, sustainable progress requires more than increasing transaction numbers. Security, affordability, financial education, and consumer protection must remain priorities.
As African economies continue embracing digital innovation, Egypt’s experience highlights an important lesson: financial technology creates lasting value when it solves practical problems and gives people greater control over how they manage their money.

Leave a reply


Africa’s Source for Breaking News | Entertainments | Health | Finance | Sports | Lifestyle and Business News.


