The Rise of Open Banking in Africa
The Rise of Open Banking in Africa: What It Means for Kenyan Entrepreneurs
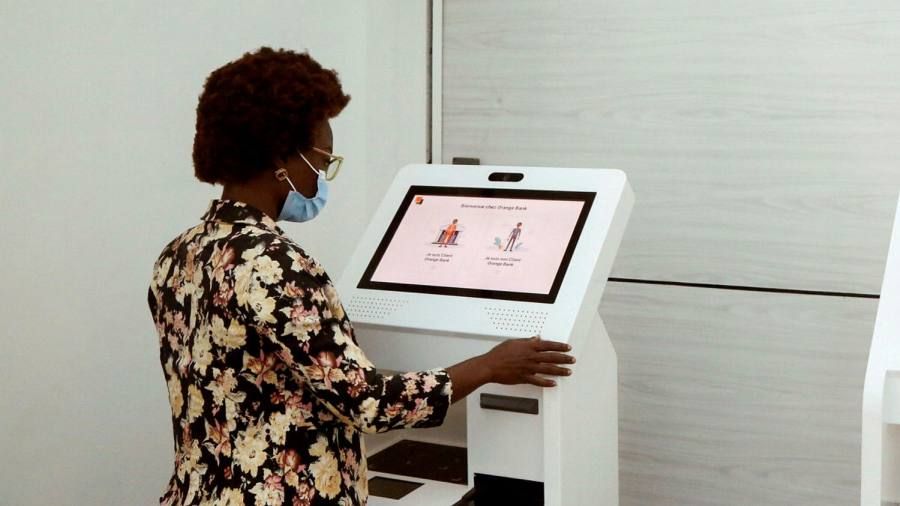
Africa’s financial sector is changing rapidly. Mobile money, digital lending, and online banking have already transformed how millions of people manage their finances. Now, another development is gaining attention: open banking. This system allows customers to share their financial information securely with authorised third-party providers, enabling new services that could make financial transactions easier and business decisions smarter.
For Kenyan entrepreneurs, open banking presents opportunities to improve cash flow management, access financing, understand customers, and build innovative financial products. Kenya already has a strong digital finance ecosystem, supported by widespread mobile money adoption and a growing technology sector. These conditions could help the country benefit from the next phase of financial innovation.
However, open banking also raises questions about data privacy, cybersecurity, regulation, and customer trust. Understanding these opportunities and risks will help entrepreneurs prepare for a financial landscape where information can become as valuable as money itself.
What Is Open Banking?
Open banking is a financial system that allows customers to authorise the sharing of their banking information with approved third-party service providers through secure digital connections, commonly known as application programming interfaces (APIs).
Traditionally, banks have controlled most of the financial information generated through their services. Customers who wanted to use another financial platform often had to provide statements manually or enter information repeatedly.
Open banking changes this arrangement. With the customer’s permission, a business application could access relevant financial information from a participating bank and use it to provide a more personalised service.
For example, a small business owner could connect several accounts to one dashboard and monitor transactions, expenses, and income without switching between different banking applications.
Open banking can also support credit assessments, payment services, financial planning, and fraud detection. However, the services available depend on the participating institutions, technical infrastructure, customer permissions, and applicable regulations.
Importantly, open banking does not mean that every company can freely access anyone’s financial information. Proper consent, security controls, and appropriate legal authorisation remain essential.
Why Kenya Is Well Positioned for Open Banking
Kenya has established itself as one of Africa’s leading digital finance markets. The success of mobile money has made electronic transactions familiar to individuals, traders, and established companies.
Services such as M-Pesa have demonstrated how digital financial tools can address practical challenges, including transferring money, paying suppliers, and receiving payments from customers. This foundation creates opportunities for businesses that want to develop more connected financial services.
Kenya’s fintech ecosystem also includes digital lenders, payment providers, savings platforms, and financial management applications. These businesses can potentially use authorised financial data to offer more useful products and improve existing services.
Nevertheless, mobile money adoption and open banking are not the same thing. A country can have extensive digital payments without having a fully developed open banking framework.
Kenya’s progress will depend on how banks, payment service providers, regulators, and technology companies establish secure data-sharing arrangements. Entrepreneurs should therefore distinguish between existing financial services and opportunities that may emerge as the regulatory and technical environment develops.
Five Ways Open Banking Could Benefit Kenyan Entrepreneurs
1. Easier Access to Business Financing
Access to affordable credit remains a challenge for many small and medium-sized enterprises (SMEs). Traditional lenders may require extensive documentation, collateral, or a lengthy business history. These conditions can disadvantage young businesses and informal traders with limited financial records.
Open banking could help address this problem by allowing entrepreneurs to share verified transaction data with authorised lenders.
Instead of relying exclusively on collateral or manually prepared statements, a lender could assess an applicant’s income patterns, customer payments, recurring expenses, and cash flow, subject to consent and applicable rules.
Consider a Nairobi-based clothing retailer that receives regular payments through different financial channels. If those records can be securely combined, a lender may gain a clearer picture of the retailer’s financial performance.
Better information could support more informed lending decisions and help eligible businesses demonstrate their creditworthiness. However, open banking does not guarantee loan approval or lower interest rates. Lenders must still assess repayment capacity, risk, and the cost of borrowing.
2. Better Cash Flow Management
Cash flow problems can threaten otherwise profitable businesses. An entrepreneur might generate strong sales but struggle to pay suppliers because customers have delayed payments or operating expenses have increased unexpectedly.
Open banking could make financial management easier by bringing information from multiple participating accounts into one platform.
Entrepreneurs could monitor incoming payments, track expenses, identify recurring costs, and receive alerts when balances fall below a certain level.
For example, a small logistics company could use an integrated dashboard to compare customer payments against fuel costs, maintenance expenses, and staff payments. This information could help management identify potential shortages before they become emergencies.
Automated reporting could also reduce the time spent reconciling transactions and preparing financial records. Entrepreneurs would then have more time to focus on sales, customer relationships, and business growth.
3. More Personalised Financial Products
Many financial products are designed around broad customer categories rather than the specific circumstances of individual businesses.
Open banking could help providers develop services that respond to actual financial behaviour.
A small retailer with seasonal sales, for instance, may need flexible financing during busy periods. A freelance designer with irregular income may benefit more from budgeting tools and automated savings features.
With permission to analyse relevant financial data, service providers could develop more appropriate recommendations, payment schedules, and financial management tools.
Kenyan fintech startups could also build specialised services for agricultural businesses, online merchants, transport operators, and other sectors with distinct financial needs.
This approach could improve the usefulness of financial products. However, providers must avoid unfair profiling, discriminatory decisions, and recommendations that encourage customers to take on unsuitable debt.
4. Faster and More Convenient Payments
Open banking can support payment innovation by connecting financial information and payment services across participating institutions.
Depending on the available infrastructure and permissions, businesses could benefit from simpler payment initiation, improved transaction reconciliation, and fewer manual steps when moving money between services.
For Kenyan entrepreneurs selling products online, convenient payments can reduce friction during checkout and improve the customer experience.
Businesses that receive payments through several channels could also benefit from automated reconciliation, making it easier to match transactions with orders and invoices.
These improvements may reduce administrative errors and help companies understand their revenue more accurately.
Still, open banking does not automatically eliminate transaction fees, guarantee instant transfers, or replace existing mobile money services. The practical benefits will depend on participating providers, payment networks, and the quality of their integration.
5. New Opportunities for Fintech Startups
Perhaps the biggest opportunity lies in the businesses entrepreneurs can build around open banking.
Developers could create applications that combine financial records, provide automated bookkeeping, assess business performance, or help small companies forecast their cash flow.
A startup might develop an accounting tool for Kenyan microbusinesses that connects authorised financial accounts and automatically categorises income and expenses. Another could help small suppliers prepare financial reports when applying for credit.
Agricultural technology companies could explore financial tools tailored to seasonal earnings, while e-commerce businesses could develop services that simplify payment tracking and financial planning.
These opportunities could create new revenue streams through subscriptions, business partnerships, or approved transaction-based services.
However, successful startups will need more than technical expertise. They must understand local business challenges, secure appropriate permissions, comply with relevant regulations, and demonstrate that their products solve genuine problems.
The Challenges Entrepreneurs Must Consider
Despite its potential, open banking comes with significant challenges.
Data privacy and cybersecurity: Financial information is highly sensitive. Businesses handling it must use strong authentication, encryption, access controls, and secure data-storage practices. A single breach could damage customer relationships and expose a company to legal consequences.
Regulatory uncertainty: Kenya’s financial sector is governed by rules covering banking, payment services, consumer protection, and personal data. The exact requirements for an open banking product depend on its activities and the institutions involved. Entrepreneurs should monitor guidance from the Central Bank of Kenya and the Office of the Data Protection Commissioner, seeking professional advice where necessary.
Integration costs: Connecting different financial systems can require considerable investment. Institutions may use incompatible technologies, data formats, and access procedures. Smaller startups may struggle to cover these costs before acquiring enough customers.
Customer trust: Some people may hesitate to share financial information with unfamiliar companies. Businesses must explain what data they collect, why they need it, who receives it, and how customers can withdraw permission where applicable.
Unequal access: Entrepreneurs in rural communities or informal sectors may have limited digital records or inconsistent internet access. Open banking will not automatically solve these structural barriers.
How Kenyan Entrepreneurs Can Prepare
Entrepreneurs do not need to wait for every part of the ecosystem to mature before taking practical steps.
First, identify a specific financial problem affecting your business or customers. Consider whether better access to authorised transaction data would genuinely improve the solution.
Second, strengthen your own financial records. Maintain accurate sales reports, separate business and personal expenses where practical, and use reliable digital bookkeeping tools.
Third, follow developments from Kenyan regulators and financial institutions. Before launching a product that accesses financial data or initiates payments, confirm the applicable licensing, consent, and data-protection requirements.
Fourth, build security into your business from the beginning. Use reputable technology providers, restrict access to sensitive information, and establish clear procedures for handling security incidents.
Finally, consider partnerships with established banks, payment providers, accounting platforms, and licensed fintech companies. Collaboration may provide a more practical starting point than building every component independently.
Conclusion
Open banking could become an important part of Africa’s evolving digital financial landscape. For Kenyan entrepreneurs, its greatest value lies in turning authorised financial information into practical business advantages, from better cash flow management and improved credit assessments to more convenient payments and innovative financial products.
Kenya’s experience with mobile money provides a useful foundation, but open banking requires additional work on regulation, secure infrastructure, interoperability, and customer trust.
Entrepreneurs who understand these requirements can position themselves to benefit as the ecosystem develops. The opportunity is not simply to gain access to more financial data. It is to use that data responsibly to solve real problems, improve financial decision-making, and build businesses that serve Kenya’s changing economy.

Leave a reply



Africa’s Source for Breaking News | Entertainments | Health | Finance | Sports | Lifestyle and Business News.


