Understanding Business Risk Management
Every business faces uncertainty.
A supplier may fail to deliver, customer demand may suddenly change, equipment may break down, or unexpected economic conditions may increase operating costs. While businesses cannot eliminate every uncertainty, they can prepare for potential problems through effective risk management.
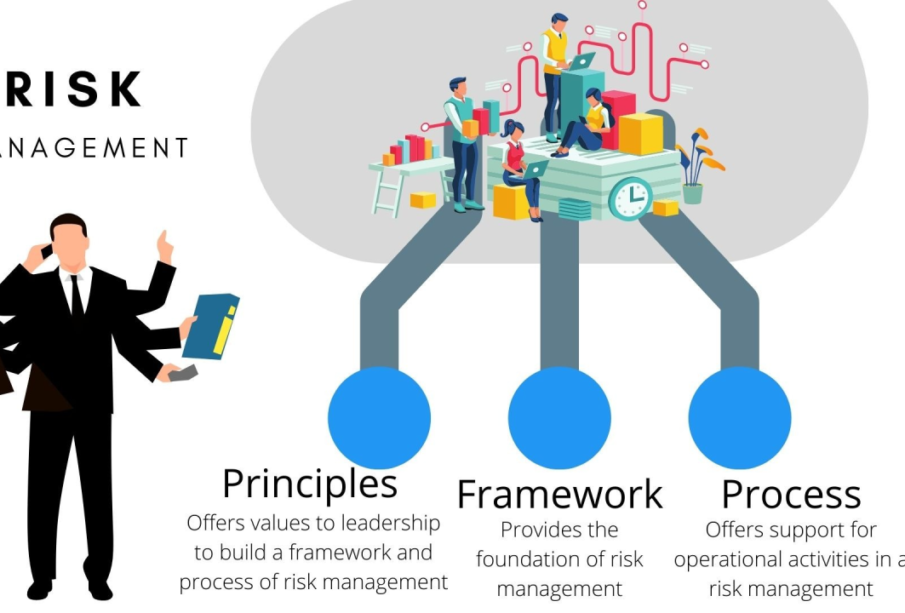
Business risk management is the process of identifying, assessing, and responding to risks that could affect an organization’s operations, finances, employees, customers, or long-term goals. For businesses of all sizes, having a clear approach to risk can improve decision-making and strengthen resilience.
What Is Business Risk Management?
Business risk management involves identifying possible events that could negatively affect a company and developing strategies to reduce their impact.
For example, a Nigerian food distributor may depend on several suppliers for essential products. If one supplier experiences production problems, the distributor could face shortages. By working with multiple suppliers, maintaining appropriate inventory, and monitoring supply conditions, the business can reduce its exposure to that risk.
Risk management is not about predicting every possible problem. Instead, it helps businesses prepare for situations that could reasonably affect their ability to operate successfully.
Why Risk Management Matters
Effective risk management allows businesses to make decisions with greater awareness of potential challenges.
One major benefit is financial protection. Businesses can identify risks that could cause unexpected losses and take steps to reduce their financial impact. This may include maintaining emergency funds, reviewing insurance coverage, or controlling unnecessary expenses.
Risk management also supports business continuity. When a company has plans for common disruptions, employees can respond more quickly when problems occur.
Another important benefit is improved decision-making. Business owners and managers can consider both opportunities and potential threats before committing resources to a new project, supplier, market, or investment.
Common Types of Business Risks
Businesses face different risks depending on their industry, location, size, and operating model. However, several categories are common across many organizations.
1. Financial Risk
Financial risks involve circumstances that could negatively affect a company’s income, cash flow, or financial stability.
Changes in customer demand, rising operating costs, unpaid invoices, currency fluctuations, and excessive debt can all create financial pressure. Businesses that rely on imported products may also experience increased costs when exchange rates change.
Maintaining accurate financial records and monitoring cash flow can help businesses identify financial problems early.
2. Operational Risk
Operational risk comes from problems within the everyday activities of a business.
Examples include equipment failure, poor inventory management, inefficient processes, workplace accidents, and disruptions in electricity or internet services.
Businesses can reduce operational risks by establishing clear procedures, maintaining equipment, training employees, and creating backup systems where necessary.
3. Market Risk
Market conditions can change quickly. Consumer preferences may shift, competitors may introduce new products, or economic conditions may reduce purchasing power.
A business that depends heavily on one product or customer group may be particularly vulnerable to market changes. Regular market research can help companies understand changing customer needs and adjust their strategies.
4. Cybersecurity and Technology Risk
Technology has become essential to modern business, but it also creates new risks.
Cyberattacks, data breaches, system failures, weak passwords, and unauthorized access can disrupt operations and damage customer trust.
Businesses should use strong passwords, access controls, software updates, backups, and employee cybersecurity training. Even small businesses can take basic steps to protect their digital systems.
5. Legal and Regulatory Risk
Businesses must comply with laws, regulations, licenses, tax requirements, employment rules, and industry standards.
Failure to meet these obligations can result in financial penalties, disputes, operational restrictions, or reputational damage. Business owners should understand the regulations relevant to their industry and seek professional advice when necessary.
6. Reputational Risk
A company’s reputation can influence whether customers, employees, suppliers, and investors are willing to work with it.
Poor customer service, misleading advertising, product quality problems, or unethical business practices can damage public confidence.
Businesses can manage reputational risk by maintaining quality standards, communicating honestly, responding professionally to complaints, and addressing mistakes promptly.
How to Identify Business Risks
The first step in managing risk is understanding what could go wrong.
Business owners can begin by examining their major activities and asking practical questions:
- What could interrupt our operations?
- What could cause significant financial losses?
- Which suppliers or customers are critical to the business?
- What happens if an important employee leaves?
- How would we respond to a technology failure?
- What external factors could affect demand?
- Which legal or regulatory requirements must we meet?
Employees can also provide valuable information because they often understand operational problems that management may not immediately notice.
Assessing and Prioritizing Risks
Not every risk requires the same level of attention. A business should consider both the likelihood of a risk occurring and the potential impact if it does occur.
For instance, a minor equipment problem that is easy to repair may require less attention than a major system failure that could stop the business for several days.
A simple risk assessment can classify risks as:
Low risk: Unlikely to cause significant disruption.
Medium risk: Could create noticeable financial or operational problems.
High risk: Could seriously affect the survival, reputation, finances, or continuity of the business.
This approach helps companies focus their limited resources on the risks that matter most.
Strategies for Managing Business Risk
Once risks have been identified and assessed, businesses can choose appropriate responses.
Avoid the Risk
Sometimes the best approach is to avoid an activity that creates unnecessary exposure. For example, a company may decide not to enter a market where the costs and uncertainties are too high.
Reduce the Risk
Businesses can introduce measures that reduce the likelihood or impact of a problem. Regular equipment maintenance, employee training, cybersecurity controls, and quality checks are examples.
Transfer the Risk
Some risks can be transferred to another party. Insurance is one common example. Contracts can also establish which party is responsible for certain risks.
Accept the Risk
Some risks are unavoidable or too small to justify expensive controls. In these situations, a business may consciously accept the risk while preparing a reasonable response if it occurs.
Creating a Business Continuity Plan
Risk management should include preparation for major disruptions.
A business continuity plan explains how the organization will continue operating during an unexpected event. It may include alternative suppliers, backup data, emergency contacts, remote-work arrangements, alternative business locations, and communication procedures.
For example, a company operating in a city where traffic and infrastructure disruptions can affect deliveries may establish multiple delivery routes and work with more than one logistics provider.
The goal is not to create a complicated document that nobody uses. The plan should be practical, accessible, and regularly reviewed.
The Role of Employees in Risk Management
Risk management is not solely the responsibility of business owners or senior managers.
Employees interact with customers, equipment, suppliers, financial systems, and business processes every day. Their observations can therefore help identify risks before they become serious problems.
Companies should encourage employees to report operational concerns without fear of unnecessary punishment. Training can also help workers understand how their actions affect business security, customer satisfaction, workplace safety, and compliance.
Risk Management for Small Businesses
Small businesses may have fewer financial resources than large corporations, but risk management is equally important.
A small business can start with simple measures. Keeping accurate financial records, separating business and personal finances, maintaining supplier relationships, backing up important files, documenting procedures, and monitoring customer feedback can make a significant difference.
Small businesses should also avoid depending entirely on one customer, supplier, employee, or sales channel where practical.
Risk Management in the African Business Environment
African businesses operate across diverse economic and infrastructure environments. Depending on the country and industry, companies may encounter challenges involving logistics, currency movements, energy supply, access to finance, changing regulations, and supply-chain disruptions.
These conditions make flexibility particularly valuable.
For example, a retailer may reduce supply risk by maintaining relationships with several wholesalers. A digital business may protect its operations by using cloud backups and alternative internet connections. A food business may reduce waste by improving inventory forecasting and storage practices.
The specific solution depends on the nature of the business. However, the principle remains the same: understand potential disruptions before they become emergencies.
Building a Risk-Aware Business Culture
Risk management becomes more effective when it becomes part of everyday business thinking.
Managers should regularly discuss potential problems, review important processes, monitor changing market conditions, and learn from previous incidents. After a disruption occurs, the company should examine what happened and determine how similar problems can be prevented or handled better in the future.
This creates a culture where employees do not simply react to problems. They actively look for ways to prevent them.
Conclusion
Business risk management is an essential part of responsible business planning. It helps companies identify potential threats, prepare for disruptions, protect resources, and make better-informed decisions.
No business can eliminate uncertainty completely. However, businesses that understand their risks and prepare appropriate responses can become more resilient when unexpected challenges arise.
For entrepreneurs and established companies alike, effective risk management should not be viewed simply as protection against failure. It is a practical tool for building a business that can adapt, recover, and continue pursuing its goals even when circumstances change.

Leave a reply


Africa’s Source for Breaking News | Entertainments | Health | Finance | Sports | Lifestyle and Business News.


